Sectors we lend to
Sectors We Lend To & Advise
Much of our work is in capital-intensive sectors, where the funding requirement is large. But a hard asset is not a requirement — we lend and arrange secured and unsecured, and asset-light businesses are funded on cash flow, contracts and counterparty strength instead.
- 16 Sectors
- Secured & Unsecured
- Global Mandates
- Dubai Headquartered
Industries we lend to
Where our mandates sit.
The sectors most of our facilities come from — each with its own conventions, and each changing something about how the facility is structured.
Energy (Oil, Gas & Downstream)
Capex runs to hundreds of millions before first revenue. Hydrocarbon exposure is priced on the downside, not the strip, across upstream, midstream and downstream facilities.
Power, Water & Renewables
Long-tenor project debt priced against a PPA or water purchase agreement, where tariff and availability decide bankability before the technology does.
Infrastructure, Transport & PPP
Concession and PPP structures, availability versus demand risk, and facilities that must hold for twenty years.
Real Estate & Mixed-Use
Where sponsor optimism and lender assumptions part company earliest, and the case has to be tested before anyone lends against it.
Hospitality & Leisure
Development funding against an operator agreement, with ADR, occupancy and ramp-up realism tested.
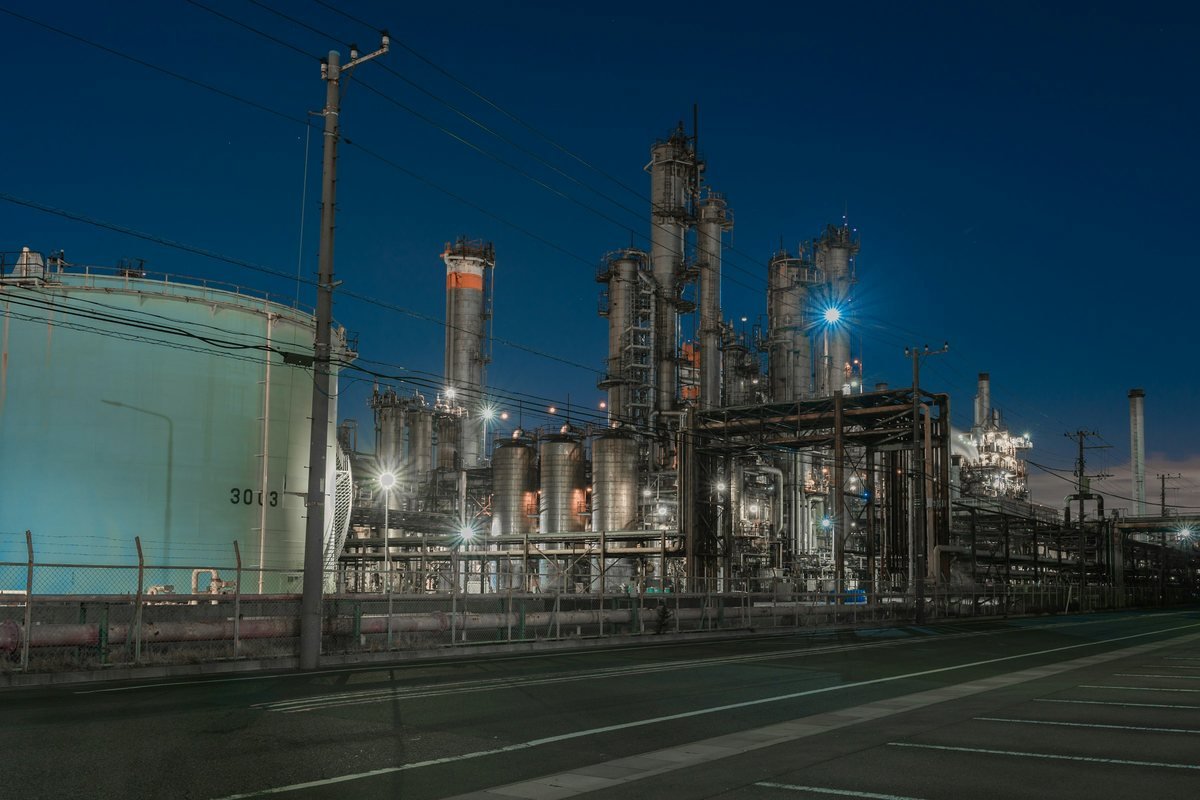
Industrial & Petrochemicals
Plant capex, feedstock security, offtake contracts and the working capital cycle behind a solvent plant.
Technology, Internet & E-commerce
SaaS, e-commerce and D2C, marketplaces, fintech lending books, data centres and tech-enabled logistics. No collateral is required: funded unsecured, against cash flow, contracts and counterparty strength.
Healthcare
Facility and equipment funding for providers and operators, where regulatory approval and patient volumes drive the case.
Agriculture & Food
Funding across production, processing and distribution, where seasonality and commodity exposure shape the structure.
Education
Facility and expansion funding for schools, training providers and campuses, tested against enrolment and fee realities.
Logistics & Trade Infrastructure
Funding for warehousing, fleet, terminals and distribution infrastructure behind regional trade flows.
Financial Services
Funding lines for lenders, brokers and financial institutions expanding their balance sheet or product range.
And the sectors not on this list
- Trade & commodities
- Retail & distribution
- Social infrastructure
Those above are where most of our facilities have come from, not the boundary of what we fund. If your sector is not listed, ask.
Where we add the most value
The same eight disciplines, in every sector.
Capital-intensive projects, asset-light businesses with no collateral, and distressed and special situations: whatever the industry, most facilities draw on these.
Direct Lending
Bridge, working capital, asset-backed, mezzanine and growth facilities written directly by RFG.
Funding Arrangement
Senior, mezzanine and bridge facilities written directly by RFG and refinanced through twelve classes of capital partner.
Project Funding
Non-recourse and limited-recourse structuring for infrastructure and large-scale developments.
Syndication & Co-lending
Clubs, syndicates and consortia where a requirement is larger than any single provider will hold.
Refinancing & Special Situations
Refinancing, take-outs, rescue and new money. Complexity does not make a company unfundable.
Due Diligence
Financial, commercial and operational review from primary sources before capital commits.
M&A & Acquisition Finance
Buy-side and sell-side execution, with the funding behind the offer arranged alongside.
Valuation & Consultancy
Valuation, feasibility and strategy work: the analysis that makes a facility bankable.
Featured industries
A closer look at five sectors we’re asked about most.
Energy finance
Oil, gas & downstream
Upstream, midstream and downstream requirements carry some of the largest facilities we see. Decisions made at final investment decision stage set the trajectory for the asset’s full life.
Financing challenges
Commodity price cycles, reserve and reservoir risk, capex running to hundreds of millions before first cash flow.
How we write it
Against contracted volume and availability, not a commodity view. Hydrocarbon exposure is priced on the downside, not the strip.
Facilities
Reserve-based lending, project debt and offtake-backed facilities, co-lent or syndicated where needed.
Typical outcome
Debt sized to the low case, with a funding line that holds through the price cycle.
Real estate lending
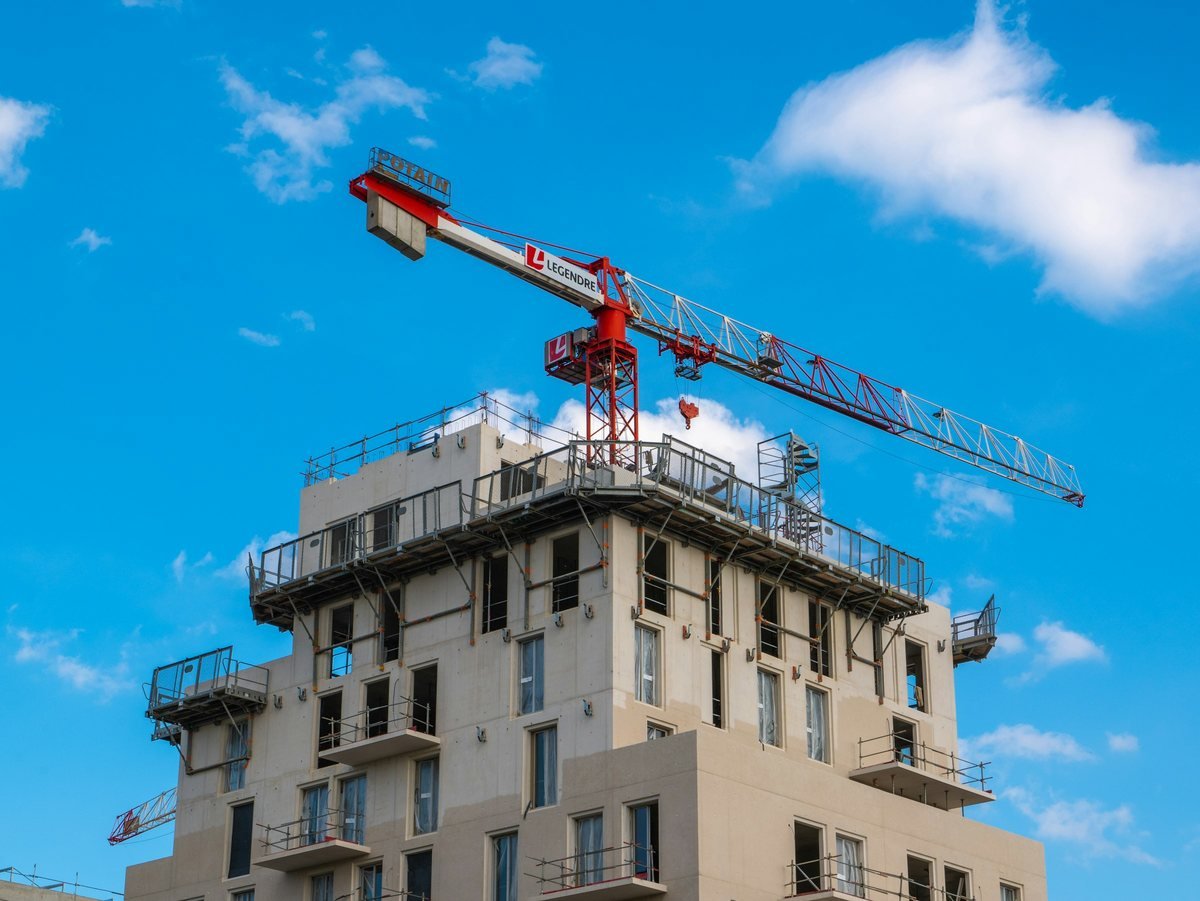
Real estate & mixed-use
Development and investment facilities across residential, commercial and mixed-use real estate, where the gap between sponsor assumptions and underwriting tends to surface earliest.
Financing challenges
Sales-velocity and absorption assumptions, construction cost overruns, exit timing.
How we write it
Sized to loan-to-cost and a defined exit, with contractor and delivery risk tested before drawdown.
Facilities
Bridge and land facilities, development finance, mezzanine and structured capital.
Typical outcome
A site secured on schedule, with the development facility drawn in phases.
Infrastructure finance
Infrastructure, transport & PPP
Transport, utilities and social infrastructure delivered through concession and PPP structures, where the facility has to hold for twenty years or more.
Financing challenges
Long construction periods, demand versus availability risk allocation, multi-party concession agreements.
How we write it
Against availability payments or tariffs, with government counterparty risk and the base case tested.
Facilities
PPP and concession financing, co-lent or syndicated with RFG taking or placing the lead.
Typical outcome
A funding package held together across government, lenders and equity sponsors to signing.
Hospitality finance
Hospitality & leisure
Hotel and leisure development and refinancing, typically structured against a management or franchise agreement with an established operator.
Financing challenges
Ramp-up risk during stabilisation, seasonality in occupancy and ADR, operator agreement terms.
How we write it
Against operator track record and realistic stabilised-year assumptions, benchmarked to market RevPAR.
Facilities
Construction-to-term facilities and operator-linked structures.
Typical outcome
Refinancing at or ahead of stabilisation, on terms tested against realistic ramp-up.
Technology lending
Technology, internet & e-commerce
No collateral is required. Technology and asset-light businesses are funded unsecured, against cash flow, contracts and counterparty strength.
Sub-sectors
SaaS and recurring revenue, e-commerce and D2C, marketplaces and platforms, fintech and lending books, data centres and digital infrastructure, technology-enabled logistics.
How we write it
On retention and unit economics, revenue quality and concentration, and the realism of the growth case.
Facilities
Revenue-based and venture debt, working-capital lines, and warehouse and forward-flow facilities for lending books.
Typical outcome
Growth funded without dilution, on a structure sized to a realistic trajectory.
Global reach
Dubai headquartered, facilities worldwide.
Capital, sponsors and counterparties pass through Dubai from every direction, and the time zone reaches most markets inside a working day. We write cross-border and multi-currency facilities, and connect UAE-based borrowers with international capital, and international borrowers with Gulf capital.
- Middle East — home market, GCC sponsors and capital
- Asia — trade finance flows, investor relationships
- Europe — institutional lenders, private credit, family offices
- Africa — cross-border trade and project finance links
- North America — institutional and alternative capital partners
- Oceania — investor relationships, Australia-Pacific mandates
Why borrowers choose us
Sector fluency, and the balance sheet to act on it.
The Structure Follows the Business
We have no single house product, so the structure follows the business. Facilities are written directly, or placed with the provider best suited to hold them.
Twelve Classes of Capital
A refinancing line behind every facility, across sovereign wealth funds, pension funds, insurers, banks’ specialty finance desks, private equity, family offices and HNIs.
Senior-Led Facilities
The transaction lead who scopes a facility runs it through to drawdown.
Secured & Unsecured
Collateral helps. It is not a precondition. Asset-light businesses are funded on cash flow, contracts and counterparty strength.
Confidential Process
The file is not circulated to reach a decision, and we sign an NDA before detailed information is shared.
Multi-Sector Expertise
One team fluent across the sectors capital gathers in, so a cross-sector transaction does not need three separate providers.
Capabilities by sector
Lending and corporate finance, structured around your industry.
Whatever the sector, most facilities draw on the same core capabilities.
- Direct lending — bridge, working capital, asset-backed, mezzanine and growth facilities written by RFG, secured and unsecured.
- Funding arrangement — senior, mezzanine and bridge facilities for energy, infrastructure and real estate.
- Project & structured finance — non-recourse structuring for infrastructure, power and large-scale developments.
- Syndication & co-lending — clubs and syndicates where a requirement exceeds a single provider.
- Refinancing & restructuring — take-outs, amendments and special situations across every sector.
- Valuation, diligence & consultancy — the analysis that makes a facility bankable.
Frequently asked
Questions about the sectors we lend to.
Energy, power, water and renewables, infrastructure and PPP, real estate and mixed-use, hospitality, industrial and petrochemicals, technology, internet and e-commerce, healthcare, agriculture and food, education, logistics, trade and commodities, retail and distribution, and financial services. Sectors outside this list are considered case by case.
No. Much of our work is in capital-intensive sectors, but a hard asset is not a requirement. We lend secured and unsecured, and asset-light businesses are funded on cash flow, contracts and counterparty strength.
Yes. SaaS and recurring-revenue businesses, e-commerce and D2C brands, marketplaces and platforms, fintech lending books, data centres and technology-enabled logistics. No collateral is required: they are funded unsecured, against cash flow, contracts and counterparty strength.
Yes. We write and arrange non-recourse and limited-recourse project finance for infrastructure, energy and real estate developments, including PPP and concession-based transactions, co-lent or syndicated where the requirement is larger than one provider should hold.
Yes. A significant share of our facilities involve counterparties, lenders or jurisdictions outside the UAE, and we write cross-border and multi-currency facilities from the Dubai headquarters.
Each sector has its own tenor expectations, security norms and cash-flow profile. Energy is written against contracted volume and priced on the downside; real estate is sized to loan-to-cost and exit; technology is funded on recurring revenue and retention. The structure follows the business.
Yes. Complexity does not make a company unfundable. We provide rescue and new money, time-critical funding and refinancing for businesses in special situations, in every sector we cover.
Send us the company, what it needs, the amount involved and what sits behind it through the contact page. Our lending team will come back within one business day.